

How Does a Chargeback Work? Complete Guide for Merchants
Learn how chargebacks work, the complete process from dispute to resolution, and proven strategies to prevent chargebacks and protect your business revenue.
15 min read
A chargeback in affiliate marketing is a forced reversal of a customer payment — one that also reverses the affiliate commission tied to that transaction.
On this page
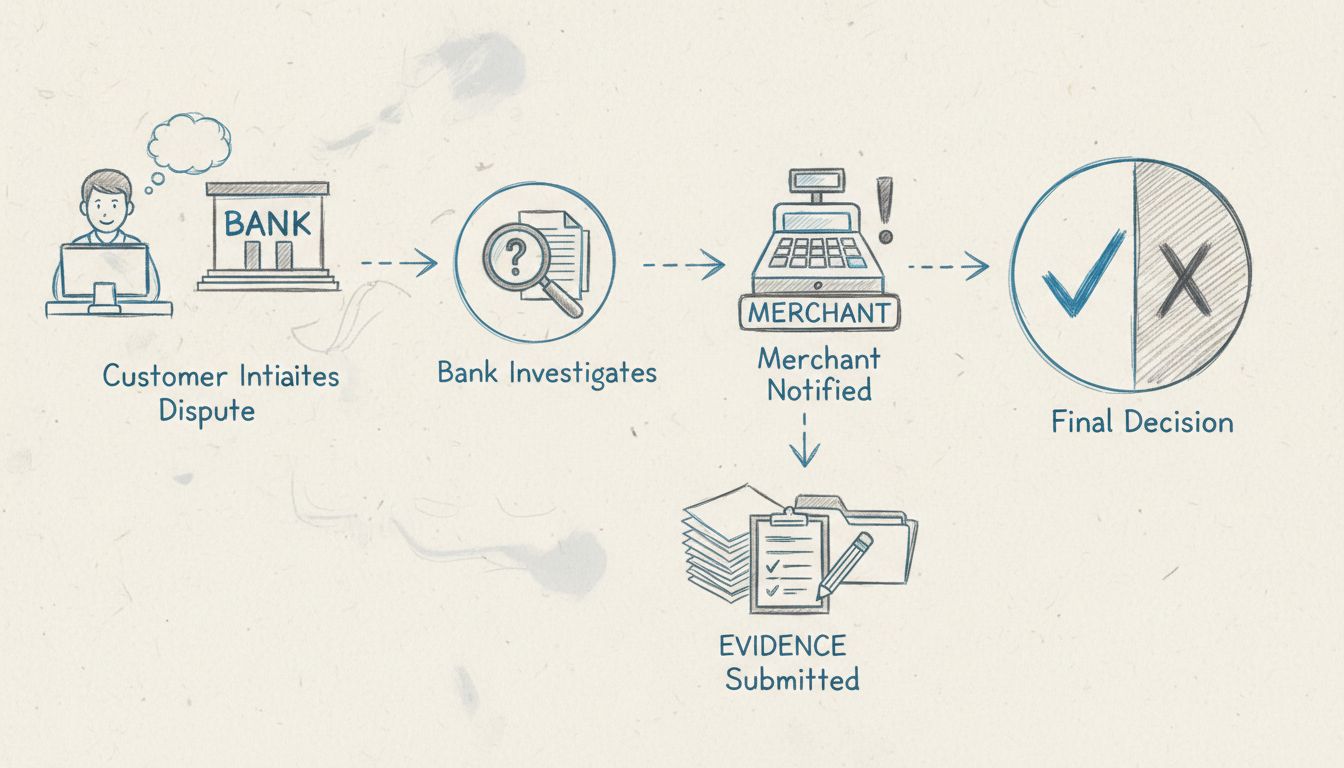
A chargeback in affiliate marketing is a forced reversal of a customer payment — one that also reverses the affiliate commission tied to that transaction. Unlike a standard refund, which the merchant voluntarily issues, a chargeback is initiated by the customer through their bank or credit card issuer. The bank investigates, and if it sides with the cardholder, it pulls the funds back from the merchant’s account.
Here is how it plays out for an affiliate:
This is not theoretical. Programs running on cost-per-sale (CPA) models are especially exposed because the commission is paid on the conversion event, not on sustained revenue. If that revenue disappears through a chargeback, the commission goes with it.
For advertisers and merchants, every chargeback is a triple loss: the product or service, the original sale revenue, and the processor’s dispute fee. Processors can impose higher reserve requirements or even terminate accounts.
For affiliates and publishers, chargebacks mean unpredictable income. A month with strong conversions can turn flat if a wave of disputes hits after payouts. Programs with aggressive clawback policies and long hold periods reduce effective earnings. High-quality affiliates who send clean, low-dispute traffic often negotiate better terms — shorter hold windows and partial clawback protection — because their referred customers rarely file chargebacks.
For affiliate program managers, chargebacks are a signal. A spike tied to one affiliate usually means fraudulent traffic, misleading creatives, or a mismatch between the offer and the audience. Programs that ignore these signals end up paying commissions on sales that never stick.

Set up advanced tracking in minutes. No credit card required.
Both reverse a sale, and both can nullify an affiliate commission. But the mechanics, costs, and consequences differ sharply.
| Factor | Refund | Chargeback |
|---|---|---|
| Who initiates it | Merchant (voluntary) | Customer, via their bank |
| Merchant’s role | Merchant agrees and processes the return | Merchant has no say — the bank decides |
| Cost to merchant | Product cost + any return shipping | — |
| Time window | — | Up to 120 days, sometimes longer |
| Impact on processor standing | None | Counts toward chargeback ratio; high ratios trigger penalties |
| Affiliate commission | Usually reversed | Almost always reversed |
A refund is a customer service outcome. A chargeback is a payment dispute that the merchant fights to win — or absorbs as a loss. For affiliates, the result is often the same: the commission disappears. But for merchants, the chargeback is far more damaging because it carries a non-refundable processor fee and harms their standing with payment providers.
Chargebacks in affiliate marketing rarely come from nowhere. They fall into predictable categories, and understanding them is the first step toward prevention.
A stolen credit card is used to make a purchase through an affiliate link. The fraudster collects the commission and vanishes before the cardholder notices the unauthorized charge. The cardholder disputes the transaction, the bank reverses it, and the merchant is left with the loss.
A real customer makes a legitimate purchase, then disputes the charge — sometimes accidentally, sometimes deliberately. Common scenarios: a family member uses the card without permission, the customer forgets about a subscription renewal, or the billing descriptor on their statement looks unfamiliar. The customer may not recognize the merchant name on their statement and assume it is fraud. Friendly fraud is harder to prevent because the transaction itself looks valid at the point of sale.
This is digital shoplifting: the customer knowingly files a false dispute to get a product for free while keeping it. Some fraudsters systematically abuse the chargeback process across multiple merchants. In affiliate marketing, some dishonest affiliates even coach buyers to file disputes after a purchase, collecting the commission either way.
Recurring billing creates a steady stream of chargeback risk. Customers forget about free-to-paid trial conversions, fail to recognize the billing descriptor on their card statement, or miss cancellation windows. Subscription-based affiliate programs see higher chargeback rates than one-time-purchase models, especially when the rebill amount is not prominently disclosed at checkout.
When an affiliate uses exaggerated claims, fake scarcity, or misleading ad copy to drive conversions, the customers who arrive are primed for disappointment. A buyer who feels tricked is far more likely to call their bank than to request a refund. These chargebacks are particularly damaging because they erode brand trust in addition to revenue.
Duplicate charges, incorrect amounts, or processing glitches can all trigger disputes. These are among the easiest to prevent through transaction monitoring and reconciliation workflows.
Be the first to know about new features and product updates.
The merchant pays. Every time.
The merchant also absorbs the operational cost of responding to the dispute, which requires gathering evidence, drafting a rebuttal, and meeting the card network’s tight response deadlines.
The affiliate does not directly pay the chargeback fee. But the affiliate’s commission on that transaction is reversed. If the commission was already paid out, the program deducts it from future earnings. So while the merchant bears the direct financial hit, the affiliate loses the compensation they earned for generating the sale.
Is a chargeback good or bad? For the customer, the chargeback system is a consumer protection mechanism — it exists to shield cardholders from fraud and unfair merchant practices. For everyone else in the affiliate marketing chain — the merchant, the affiliate, and the program manager — a chargeback is unambiguously bad. It represents a sale that failed, revenue that disappeared, and a commission that was never truly earned.
Chargeback fraud in performance marketing follows three well-established patterns. In every case, the affiliate collects the commission and the advertiser absorbs the loss.
The most direct form of affiliate fraud: a fraudster uses stolen card credentials to complete a purchase through their own affiliate link. They earn the commission. When the legitimate cardholder discovers the unauthorized charge and files a dispute — which can happen weeks or months later — the commission has already been paid. The merchant loses the product, the revenue, and the commission, plus a chargeback fee.
Automated scripts or botnets generate fake sales using synthetic or compromised payment methods. These transactions may look legitimate at conversion time but trigger bulk chargebacks once the fraud is detected. Because bot traffic can scale quickly, a single campaign can generate hundreds of chargebacks before the pattern is caught.
Some affiliates actively encourage buyers to dispute charges. They may promise a refund after purchase or incentivize the buyer with the expectation that both the product and the chargeback will work out in the buyer’s favor. The affiliate collects the commission, and by the time the chargeback hits, they have moved on.
Visa, Mastercard, and other card networks use structured reason codes to classify chargebacks. For an affiliate-fraud sale, the most common codes are:
Knowing which code applies matters because the evidence required to fight the dispute differs by code. An authorization-based dispute demands proof that the cardholder participated in the transaction. A non-delivery dispute needs tracking data and delivery confirmation.
Prevention works best when it starts before conversions are even recorded, not after disputes arrive.
Delay affiliate payouts by 30 to 90 days after the transaction. Most chargebacks surface within 60 days, so a hold period lets the program identify and deduct reversals before money leaves the account. For affiliate programs in high-risk verticals like nutraceuticals, iGaming, or subscription software, these buffers are standard practice.
Watch for sudden spikes in conversion volume from a single affiliate, especially if the conversion rate looks too good to be true. Flag traffic sources with high ratios of international IP addresses, disposable email domains, or mismatched billing and shipping addresses. Traffic anomalies are the earliest warning sign of fraudulent conversions.
Your affiliate agreement should spell out exactly when commissions are reversed, how long the clawback window lasts, and what behavior triggers a ban. Prohibit incentivized traffic, forced clicks, and misleading claims in promotional materials. Affiliates who know the terms will have their payouts clawed back for chargebacks are less likely to send risky traffic in the first place.
One of the most preventable causes of chargebacks is a billing descriptor on the customer’s card statement that does not match the storefront they remember buying from. Match your descriptor to your brand name, include a phone number, and keep it consistent. When customers recognize the charge, they call you instead of their bank.
Device fingerprinting, IP reputation scoring, and velocity checks catch fraudulent transactions before they complete. Modern fraud detection platforms flag mismatched geolocation data, proxy usage, and patterns that suggest automated conversions. Integrating these tools with your affiliate tracking software closes the gap between when a sale is recorded and when it is paid.
Many chargebacks are filed because the customer could not reach anyone to resolve their issue. Offer live chat, publish a clear refund policy, and make cancellation easy — especially for subscription products. A customer who can quickly request a refund through your support team will not escalate to a bank dispute. Merchants with accessible, responsive customer service consistently see lower dispute rates.
Periodically review how your affiliates are promoting your products. Check their landing pages, ad copy, and social media posts for exaggerated claims or misleading language. An affiliate who promises a “free trial” without disclosing the rebill terms is generating conversions that will almost certainly chargeback. Paid traffic sources deserve extra scrutiny — verify that the audience targeting matches your offer.
When a chargeback lands, the clock is ticking. Card networks allow 10 to 30 days for a merchant response depending on the reason code. Here is the evidence to gather:
If the evidence shows the transaction was legitimate but the affiliate used deceptive methods to drive it, the merchant may still lose the dispute. That is why prevention — catching these patterns before commissions are paid — is more effective than fighting chargebacks after the fact.
Not every chargeback means intentional fraud. A single dispute could be a legitimate customer who forgot about a subscription or did not recognize the billing descriptor. But patterns matter.
Drop the affiliate immediately if:
Investigate before acting if:
Program managers who track chargeback rates per affiliate — not just overall — can spot problems early.
Yes. It has been a persistent problem since the earliest days of performance marketing, and it evolves as detection tools improve. The most common forms — cookie stuffing, click fraud, and stolen-card purchases — cost the industry billions annually. Some affiliate fraud is easy to spot; other forms, like sophisticated device spoofing, require specialized detection tools to uncover.
The good news: modern affiliate tracking platforms and fraud detection services have made it far harder for fraudsters to operate at scale than it was a decade ago.
Filing a chargeback for a legitimate reason — an unauthorized transaction, a product that never arrived, or a good that was significantly not as described — is legal and protected by consumer protection laws in the United States and most jurisdictions.
Filing a chargeback with false information to get a product for free is chargeback fraud — and it is illegal. It can be prosecuted as theft, wire fraud, or credit card fraud depending on the jurisdiction and the dollar amount. Merchants can also pursue civil action against repeat offenders.
For affiliates, knowingly driving fraudulent sales that result in chargebacks can violate both the affiliate program’s terms and applicable law. Affiliates who use stolen credit cards to generate commissions are committing criminal fraud, not just breaking program rules. Can a merchant get in trouble for an affiliate’s fraud? Yes — merchants can face penalties from payment processors, fines from card networks, loss of their merchant account, and in severe cases, regulatory action if they fail to police fraudulent affiliates effectively.
Discover best practices and tools to reduce chargebacks, protect your earnings, and build trust in your affiliate program.
Learn how chargebacks work, the complete process from dispute to resolution, and proven strategies to prevent chargebacks and protect your business revenue.
Post Affiliate Pro automatically handles refunds and chargebacks by adjusting affiliate commissions accordingly. Protect your business from paying commissions o...
Learn what commission reversal rate means, how it works, and which calculation, tracking, or program rules affect affiliate results.
Join our community of happy clients and provide excellent customer support with Post Affiliate Pro.
Cookie Consent
We use cookies to enhance your browsing experience and analyze our traffic. See our privacy policy.